Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
TSMC just put up the best quarter in its history. Its stock went down anyway.
On Thursday, Taiwan Semiconductor Manufacturing reported third-quarter 2026 net income of NT$763.06 billion (about US$23.6 billion), up 68.7% from a year earlier, on revenue of US$46.72 billion, up 41.2%. It was the company’s sixth straight record-profit quarter, and it beat the LSEG SmartEstimate of NT$746.3 billion, according to Reuters via Investing.com. Management also raised its full-year growth forecast to about 44% in dollar terms and guided fourth-quarter sales to as much as $54.3 billion.
And yet the US-listed shares (ticker TSM) traded roughly 2% to 4% lower during Thursday’s session, after a 3.4% drop on Wednesday. So what’s going on? Mostly, it’s not about TSMC. It’s about rates, chip stocks in Asia and a market that suddenly wants proof AI spending pays off. Let’s unpack the TSMC Q3 2026 earnings and what they mean for your portfolio.
Here’s the year-over-year picture, using TSMC’s own Q3 2026 press release and its Q3 2025 filing with the SEC.
| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue (US$) | $33.10B | $46.72B | +41.2% |
| Revenue (NT$) | NT$989.9B | NT$1,494.2B | +50.9% |
| Net income (NT$) | NT$452.3B | NT$763.1B | +68.7% |
| Earnings per ADR | $2.92 | $4.60 | +57.5% |
| Gross margin | 59.5% | 66.4% | +6.9 points |
| Operating margin | 50.6% | 58.7% | +8.1 points |
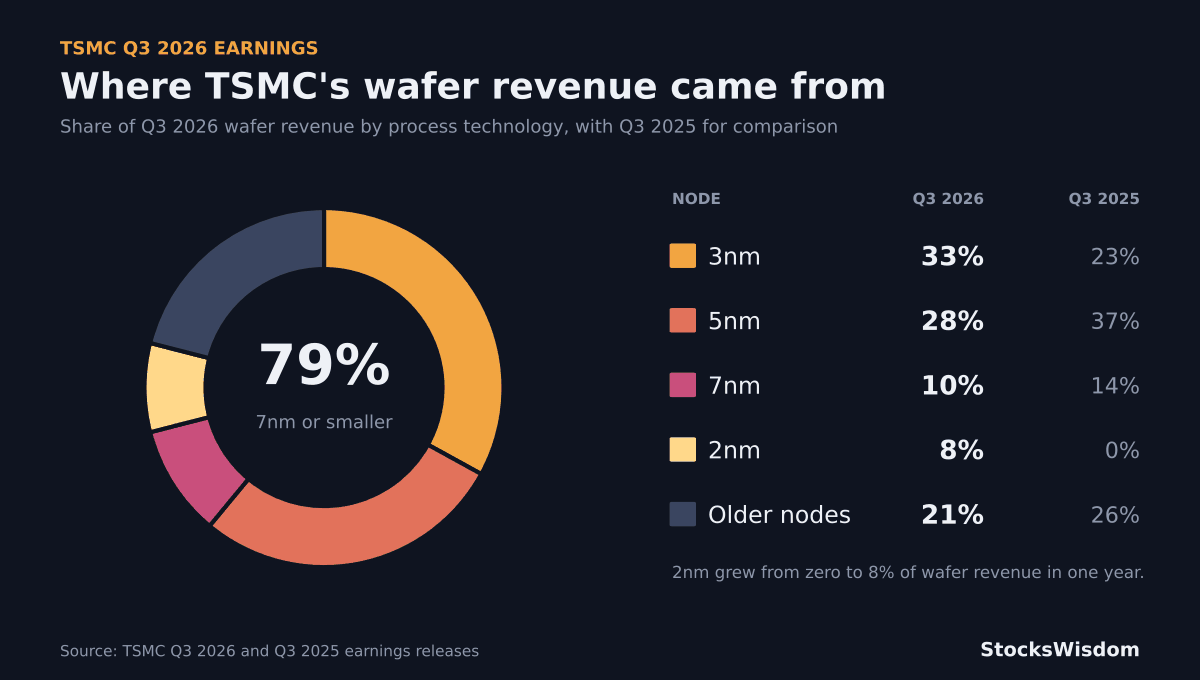
| 3nm share of wafer revenue | 23% | 33% | +10 points |
A net profit margin of 51.1% is wild for a company that makes physical things in factories. More than half of every dollar of sales ended up as profit.
Wall Street had penciled in about $4.42 per ADR. TSMC delivered $4.60.
Three things hit at once.
First, rates. Wednesday’s consumer price index showed inflation at 3.7% year over year, a touch above forecasts. Then Thursday’s producer price index came in at 6.3% versus 5.5% expected, the biggest jump since 2022. One analyst quoted by TheStreet said the data “all but confirms” another Fed hike, and markets now treat the next meeting as roughly a coin flip. High-multiple tech stocks hate that.
Second, Asia had a brutal night. South Korea’s Kospi closed 8% lower, with SK Hynix down 11% and Samsung down 9%. Japan’s Nikkei fell 5%. When the whole chip complex sells off, even the strongest name gets dragged.
Third, margins slipped. Gross margin fell to 66.4% from 67.7% in the second quarter, and fourth-quarter guidance of 65% to 67% doesn’t promise a rebound. CFO Wendell Huang said the dip came mainly from the early ramp of 2nm chips, which are expensive to make before yields improve.
Add the fact that TSM was up more than 41% for the year going into Wednesday, and you get a classic “sell the news” setup.
If you were worried TSMC would hint at an AI slowdown, it did the opposite. On the call, Wei described demand for leading-edge chips as extremely strong and added, “We did not see any sign of slowdown,” as reported by Techloy.
He pointed to agentic AI (software agents that carry out tasks on their own) as a fresh driver, lifting demand for AI accelerators, server CPUs and networking chips.
The money is following. TSMC kept its 2026 capital spending budget at $60 billion to $64 billion, and Huang said spending from 2026 through 2028 will be “even more significantly higher than the past three years,” per Yahoo Finance. Companies don’t pour that kind of cash into factories unless customers are committing to fill them.
High-performance computing, the bucket that holds AI chips for customers like Nvidia, made up 68% of revenue in the quarter and grew 22% from the second quarter. Smartphones (think Apple) were 21%. Autos and connected devices were 4% each.
The node mix tells the same story. Chips built on 7nm or smaller produced 79% of wafer revenue, and the newest 2nm process already contributed 8% in its first full year of volume production. The chart below shows how TSMC’s third-quarter wafer revenue split across its chip technologies.
A brand-new manufacturing process is like a new restaurant kitchen. The first few months are slower and messier, so each meal costs more to make. As the staff gets faster, costs fall.
That’s what’s happening with 2nm. TSMC is also building plants in Arizona, Japan and Germany, where costs run higher than in Taiwan. Huang put that drag at about 2 percentage points of gross margin today, widening to 3 to 4 points over the next several years.
None of that is alarming for a company sitting at 66% gross margin. But it does mean the huge margin gains of the past year probably won’t repeat. Investors who priced in perfection are adjusting.
You probably own TSMC already, even if you never bought it. It’s one of the largest holdings in many semiconductor ETFs and international funds, and it shows up in plenty of emerging-markets index funds too.
A few practical points:
If you’re watching chip names through this volatility, StocksWisdom shows a stock’s sentiment, technical signals and 30-day forecast in one place, which can help you tell a sector-wide pullback from a company-specific problem.
The drop was mostly about the market, not the report. Hot inflation data raised the odds of another Fed rate hike, Asian chip stocks sold off hard and TSMC’s gross margin dipped a bit from the prior quarter. The stock had also gained more than 41% this year, so some investors took profits.
It manufactures chips that other companies design. Nvidia, Apple, AMD and many others send TSMC their designs, and TSMC builds them in its fabs. It doesn’t sell chips under its own brand.
Not yet. The decline came mainly from ramping the new 2nm process and from pricier overseas plants. A 66.4% gross margin is still far above where TSMC was a year ago (59.5%). Watch whether it holds inside the 65% to 67% guidance next quarter.
So here’s my question for you: is this pullback a gift for long-term chip investors, or the start of the market demanding real AI profits? Tell us in the comments.
Not financial advice. Do your own research.