Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
The Federal Reserve raised interest rates last Wednesday for the first time since 2023, and the 10-year Treasury yield has been hovering around 5%, close to its highest level since 2007. If you’ve never paid attention to bonds, this is a good moment to start.
Five percent from the U.S. government sounds like a great deal. In some cases it is. But bonds have a catch that a lot of first-time buyers miss, and it explains why some people lost money on “safe” bonds over the last few years.
This guide covers how Treasury yields work, why bond prices fall when rates rise, which type of Treasury fits which goal, and how to buy one.
When you buy a Treasury, you’re lending money to the U.S. government. In return you get interest, and your money back when the bond matures.
The yield is the annual return you lock in if you buy at today’s price and hold to the end. The “10-year Treasury yield” you hear about on the news is the return on a government bond that matures in ten years.
That one number matters well beyond the bond market. Banks use it to set mortgage rates, companies borrow against it, and investors compare every other investment to it. When it climbs, borrowing gets more expensive almost everywhere.
This is the part that trips people up.
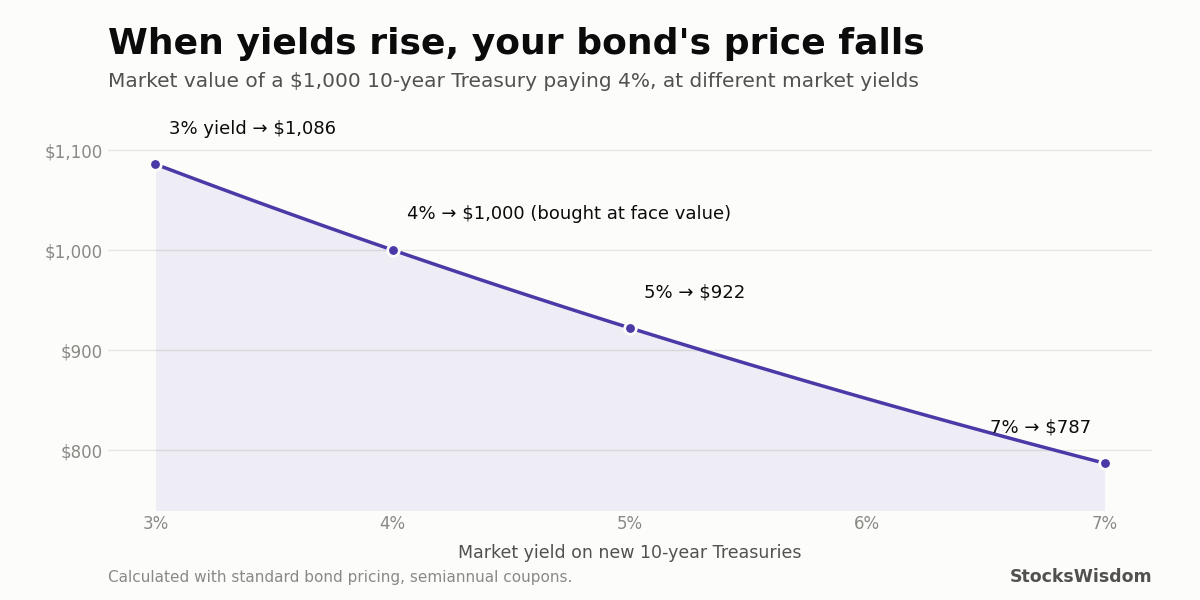
Say you bought a 10-year Treasury for $1,000 that pays 4% a year. Then rates rise and new 10-year bonds pay 5%. Nobody will pay you the full $1,000 for your 4% bond when they can get 5% elsewhere. To sell it, you’d have to cut the price to about $922. That’s a loss of nearly 8% on paper, even though the government never missed a payment.
It works in reverse too. If yields dropped to 3%, that same bond would be worth about $1,086.
The chart below shows the full relationship for a 10-year bond paying 4%.
The good news: if you hold the bond until it matures, you still get your full $1,000 back plus every interest payment. The price only matters if you sell early, or if you own a bond fund, which reports these price changes every day.
How much a bond’s price moves depends mostly on how long it has left. Using the same 4% bond and a one-point jump in rates (4% to 5%):
This is called duration risk, and it’s why long-term bond funds had such a rough stretch when rates rose. Charles Schwab’s fixed income team currently suggests favoring short- and intermediate-term bonds for that reason (Schwab).
Treasuries come in different lengths, and the right one depends on when you’ll need the money.
| Type | Matures in | Rough yield (mid-Sept 2026) | Price risk | Good for |
|---|---|---|---|---|
| T-bill | 4 to 52 weeks | about 4% | Very low | Emergency fund, cash you need within a year |
| 2-year note | 2 years | about 4.7% | Low | Money for a goal 1 to 3 years out |
| 10-year note | 10 years | about 5% | Medium | Locking in income, if you can hold to maturity |
| 30-year bond | 30 years | above 5% | High | Long-term income, or a bet that rates will fall |
One detail people miss: interest on Treasuries is exempt from state and local income tax. If you live in a high-tax state like California or New York, a Treasury can beat a CD or savings account that pays slightly more on paper.
You have three main options:
For most beginners, buying individual T-bills or 2-year notes through a brokerage is the simplest way to start.
When a risk-free bond pays 5%, stocks have to work harder to look attractive. Investors start asking whether a company’s growth is worth the extra risk compared with a guaranteed return.
That’s why rate-sensitive stocks, like unprofitable tech companies, small caps and real estate, often struggle when yields climb. Companies with steady cash flow tend to hold up better.
It doesn’t mean you should sell your stocks and move everything into bonds. It means the trade-off is real again after years of near-zero rates. If you’re weighing a stock against a 5% Treasury, StocksWisdom can show you the stock’s 30-day forecast and risk score, which makes that comparison a little more concrete.
Only if you sell before maturity after rates have risen, or if you own a bond fund. Hold an individual Treasury to the end and you get all of your money back plus interest.
Yields are the highest they’ve been in almost two decades, which locks in more income than at any point in years. The risk is that rates keep rising after you buy. Shorter maturities limit that risk.
The interest rate (the coupon) is fixed when the bond is issued. The yield changes with the bond’s market price. Buy below face value and your yield is higher than the coupon. Buy above it and your yield is lower.
Not financial advice. Do your own research.