Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
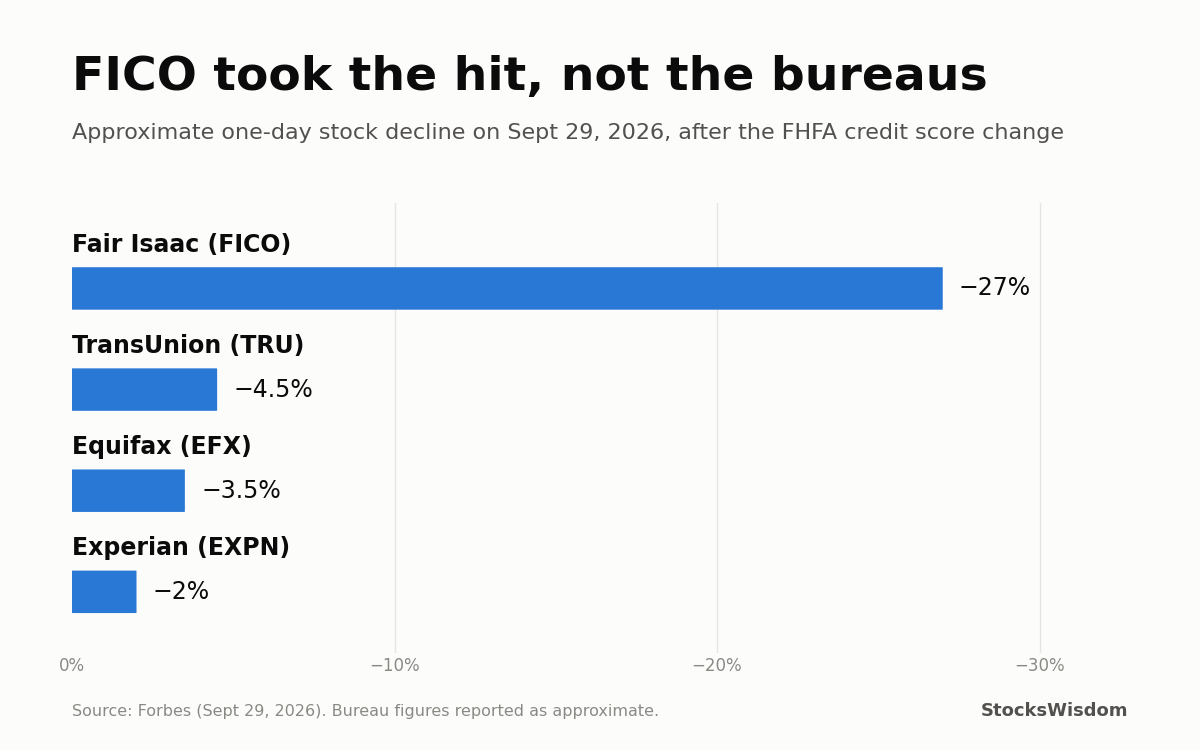
Fair Isaac, the company behind the FICO score, lost about a quarter of its stock market value on Tuesday. It was one of the worst single days for a large software company this year, and it had nothing to do with earnings.
The trigger was a rule change for mortgages. On Monday evening, the Federal Housing Finance Agency (FHFA) said Fannie Mae and Freddie Mac will combine their mortgage pricing grids into one that includes both VantageScore and FICO. The same day, Rocket Mortgage said it would make VantageScore its preferred credit score on all eligible loans.
If you own FICO stock, this hurt. If you’re planning to buy a home, it could quietly help. Here’s what changed in the VantageScore vs FICO fight, and what it means for both groups.
Most U.S. mortgages are bought by Fannie Mae and Freddie Mac, and they set the rules lenders follow. For decades, that meant one score: FICO.
That started to change on September 9, when the FHFA said lenders no longer needed special approval to use VantageScore 4.0 on eligible loans. But there was a catch. Fannie and Freddie still priced loans using separate grids, which in practice kept FICO as the default.
FHFA Director Bill Pulte said that two-grid setup “makes zero sense,” and on Monday the agency announced a single grid covering both scores (Forbes). No start date has been given yet.
Then the lenders moved. Rocket Mortgage, one of the largest home lenders in the country, said it will use VantageScore 4.0 as its preferred model on all eligible loans. TransUnion said it will charge 99 cents per VantageScore mortgage score through December 2028.
FICO’s mortgage business has been a near-monopoly. Lenders had no real alternative, so FICO could raise its prices and lenders mostly had to pay.
Investors valued the company that way. A stock with pricing power like that trades at a high multiple, because the market assumes those profits keep growing for years.
A real competitor changes the math. FICO doesn’t have to lose every customer for the stock to drop. It only needs investors to believe it can’t keep raising prices the way it used to. That’s what Tuesday priced in.
VantageScore 4.0 was used on roughly 9% of mortgages Fannie and Freddie reviewed between May and August. That’s small today. With one big lender switching and a 99-cent price on the table, the question is how fast it grows.
The credit bureaus slipped too. TransUnion fell about 4.5%, Equifax more than 3.5% and Experian more than 2%. They sell data used in both scores, so they’re less exposed than FICO, but the market is reading this as more pressure on the whole credit-score chain.
You won’t have a new score overnight. Both models use the same credit reports from the bureaus. They weigh things differently, though:
For most borrowers with a long, clean record, the difference will be small. For people with short credit histories, it could decide whether they qualify for a loan at all.
Every mortgage pulls credit scores, and the fees get passed to the borrower at closing. FICO’s per-score price for mortgages has risen sharply in recent years, which is a big reason regulators got involved.
If lenders can choose between two scores, they can push back on price. A few dollars per score won’t change your monthly payment. But it’s one of many closing costs that has been creeping up, and competition tends to push those down over time.
Don’t expect lower mortgage rates from this, though. Rates follow the bond market, and the 10-year Treasury yield is still above 5%.
This is a lesson in how fast a “moat” can shrink. FICO didn’t miss earnings or lose a lawsuit. One regulator changed one rule, a big customer switched, and a quarter of the company’s value disappeared in a day.
A few things to watch from here:
FICO also has a large business outside mortgages, in credit cards, auto loans and fraud software. Some investors will argue the selloff overshot. Others will say the mortgage business was what justified the old valuation. Both views have a case.
It’s also worth keeping the bigger picture in mind. The Conference Board’s consumer confidence index fell to 81.9 on Tuesday, its lowest level since 2014, with people pointing to high prices and gas costs (Investing.com). Housing is already slow. A cheaper credit check helps at the margin. It won’t fix affordability on its own.
If you’re watching FICO, TransUnion or Equifax after this move, StocksWisdom shows the 7-day and 30-day forecasts and news sentiment for each, which helps tell a lasting change from a one-day overreaction.
So which side are you on: did the market overreact to FICO, or is this the start of a longer decline?
Not financial advice. Do your own research.