Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Nike stock is trading around $33 a share. It started the year near $64, so it’s down roughly 45% in 2026 alone, and it’s at levels last seen more than a decade ago (Quartz). Last week’s earnings report didn’t help. Shares fell again after Nike warned that sales will shrink this year.
For one of the most famous brands on the planet, that’s a stunning fall. So what went wrong, what did the latest numbers actually say, and is Nike stock a bargain or a trap? Here’s a clear breakdown.
Nike’s fiscal first quarter ended August 31. The results came out on October 1 (StockTitan):
The quarter itself was mixed. The outlook was the problem. A big one. Investors had hoped this would be the year sales stabilized. Instead Nike told them to expect another decline.
The weakness isn’t spread evenly. The chart below shows how each part of the business changed from a year ago.
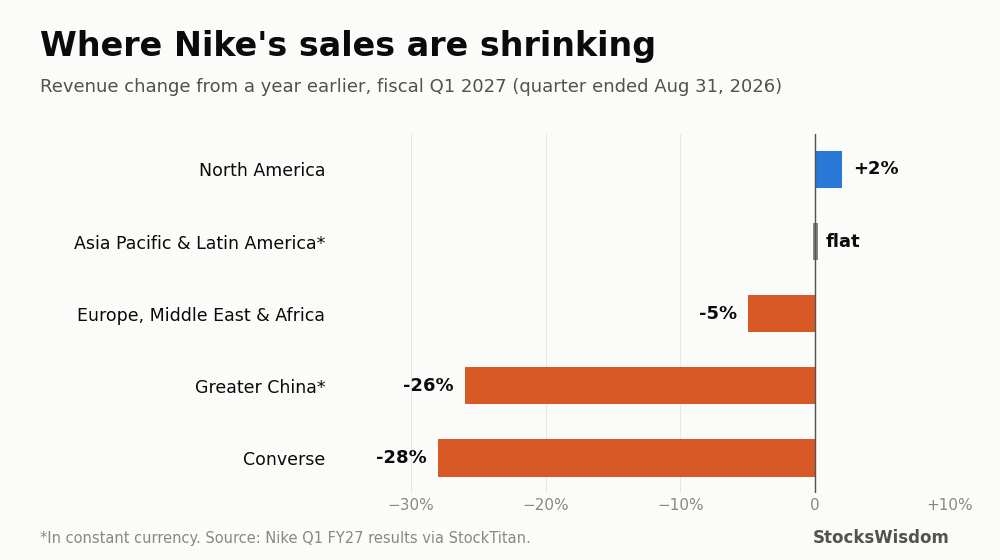
Greater China is the biggest problem. Sales there fell 26% in constant currency, and profit in the region dropped 34%. Local brands have been winning over Chinese shoppers, and Nike hasn’t found an answer yet.
Converse is shrinking fast. Revenue fell 28% to $263 million.
Nike’s own stores and app are slipping. Nike Direct sales fell 8%, with digital down 13%. For years Nike pushed customers toward its own channels and pulled back from retailers. Under CEO Elliott Hill, who took over in 2024, it’s been rebuilding those wholesale relationships, and wholesale in North America rose 9%.
North America is the bright spot. It was the only region that grew, up 2% to $5.13 billion.
Tariffs are another headwind. New duties of 12.5% on goods from China and Vietnam and 10% on goods from Indonesia took effect in July. Those are three of Nike’s most important manufacturing countries.
Alongside the results, Nike laid out a turnaround program called Pace. It reorganizes the company into three regions, modernizes the supply chain and is meant to save about $2.5 billion through fiscal 2031. It comes with roughly $1 billion in charges along the way, and job cuts are part of it.
Cost cuts can protect profits. They don’t fix demand. The real question is whether Nike can make products people line up for again, especially in running and sportswear, where newer brands have taken share.
Here’s a detail worth paying attention to if you own Nike for income.
Nike pays $0.41 a share every quarter, or $1.64 a year. That’s about a 4.8% yield at today’s price, which looks attractive. Nike has also raised its dividend for 24 years in a row.
But compare that $1.64 to the earnings guidance of $1.15 to $1.35 a share. Nike expects to pay out more in dividends than it earns this year, a payout ratio of roughly 120% to 140%. In the first quarter alone, dividends ate up about 86% of net income.
A company Nike’s size can afford that for a while, using cash and debt. It can’t do it forever. If profits don’t recover, the dividend streak could come under pressure. That’s worth knowing before you buy the stock for its yield.
The case for buying: Nike is still the biggest sportswear brand in the world. Margins are improving, North America is growing again and the stock trades far below its past highs. The Motley Fool points out that Nike has bounced back from deep slumps before, including in 2015 and 2016, 2022 and 2024 (The Motley Fool).
The case for waiting: Sales are still shrinking, China keeps getting worse and analysts have been cutting their ratings. Bank of America rates the stock Underperform with a $30 price target. A cheap stock can get cheaper when the business is still declining.
A reasonable middle path: if you believe in the brand, you don’t have to buy all at once. Nike holds an Investor Day on November 16 and 17, where management is expected to give more detail on the turnaround. That’s a natural checkpoint before committing more money.
You can track how sentiment around NKE shifts into that event on StocksWisdom, which shows the stock’s news sentiment and 30-day forecast side by side.
Nike isn’t going away, but the turnaround is taking longer and costing more than investors hoped. Would you buy Nike at a decade-plus low, or wait for proof that sales have turned?
Not financial advice. Do your own research.