Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
AMD just posted the kind of quarter chip investors have been waiting two years to see. Revenue hit a record $13.38 billion, up 45% from a year ago, and the data center business nearly doubled to $8.55 billion. Adjusted earnings came in at $2.09 a share, ahead of the $1.94 Wall Street expected.
Then came the part that really moved the stock. AMD guided fourth-quarter revenue to about $17 billion, plus or minus 3%, while analysts had penciled in roughly $16.23 billion, according to Investing.com. Shares, already up 3.65% in the regular session, jumped more than 7% after hours.
So what’s actually driving this, what could go wrong, and what does it mean if you own AMD (or a chip ETF that does)? Let’s go through it.
Here’s how the quarter stacks up against estimates and against last year, using figures from AMD’s official earnings release.
| Metric | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Revenue | $13.38B | $9.25B | +45% |
| Adjusted EPS | $2.09 | $1.20 | +74% |
| GAAP EPS | $1.46 | $0.75 | +95% |
| Adjusted gross margin | 56% | 54% | +2 pts |
| Adjusted operating margin | 29% | 24% | +5 pts |
| Data Center revenue | $8.55B | $4.34B | +97% |
Revenue beat the $13.06 billion consensus by about $300 million. That’s a clean beat, not a squeaker.
Profit grew much faster than sales, too. GAAP operating income more than doubled to $2.83 billion. When revenue rises 45% and operating income rises 123%, it tells you each extra dollar of sales is landing on a business whose fixed costs are already paid for.
A few years ago AMD was mostly a PC and gaming chip company. Not anymore. Data center sales made up about 64% of revenue this quarter, up from 47% a year earlier.
Two product lines did the work. EPYC server processors kept taking share in cloud data centers, and the new Instinct MI450 Series GPUs (AMD’s answer to Nvidia’s AI accelerators) started shipping. CEO Lisa Su said demand for Instinct and EPYC “continued to strengthen,” and that she expects growth to “accelerate further in the fourth quarter as we scale Helios and ‘Venice’ production,” per the release on Yahoo Finance.
Helios is AMD’s full rack-scale AI system, a whole cabinet of GPUs and CPUs built to work as one machine. The company says Anthropic, Meta, Microsoft, OpenAI and Oracle’s cloud are already running models on the first Helios systems. Investing.com also pointed to a six-gigawatt agreement with Meta to power AI infrastructure with AMD GPUs.
The segment is also very profitable. Data center operating income was $2.88 billion, up from $1.07 billion a year ago.
Not every business grew. The graphic below shows how each segment’s revenue changed from Q3 2025 to Q3 2026, and you can see one line pointing down hard.
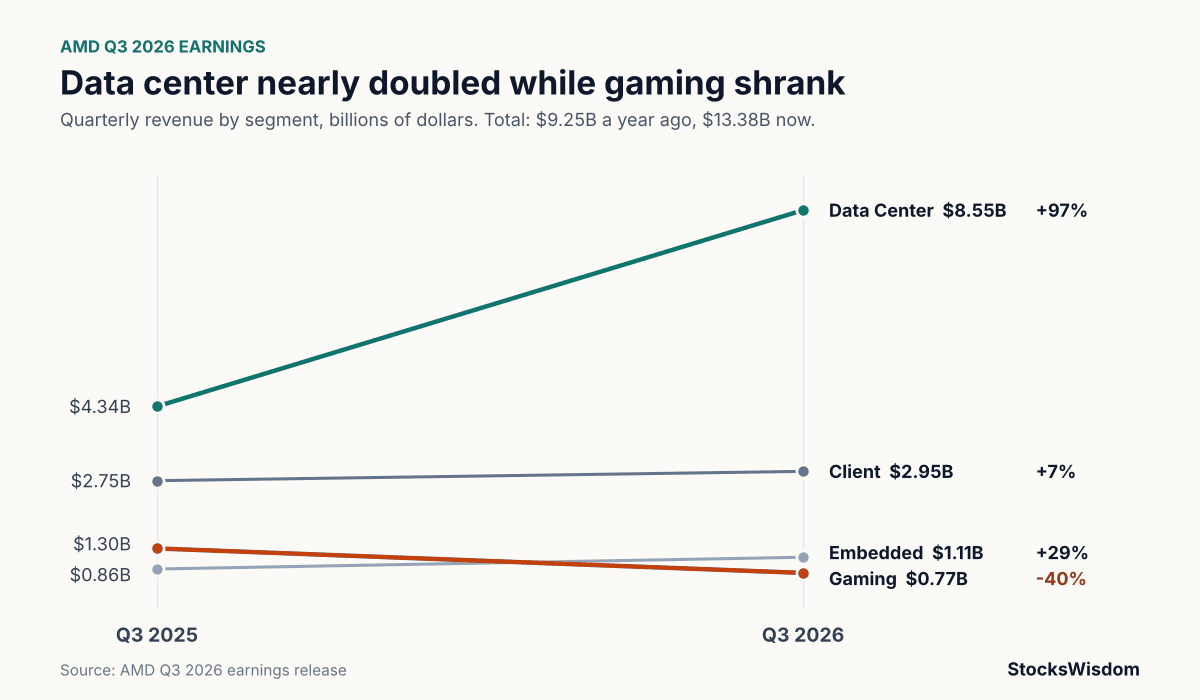
Gaming revenue dropped 40% to $773 million on weaker semi-custom sales (the chips inside game consoles) and graphics cards. Console cycles age, and this one is old.
Client, which is mainly Ryzen laptop and desktop chips, grew 7% to $2.95 billion. Embedded, the chips that go into cars, factories, telecom gear and defense systems, rose 29% to $1.11 billion after a slow couple of years.
Gaming is now under 6% of sales. A 40% drop there barely dents the total, which is exactly why the market shrugged it off.
Stocks trade on the future, and AMD’s outlook is aggressive. A $17 billion midpoint implies roughly 66% growth from a year ago and about 27% growth from the quarter it just reported.
That’s a huge sequential jump for a company this size. It also means AMD expects Helios shipments to ramp fast in the next 90 days, and any hiccup in supply, packaging or customer timing would show up quickly.
| Q4 2026 outlook | AMD guidance | Analyst consensus |
|---|---|---|
| Revenue | $16.5B to $17.5B | about $16.23B |
| Adjusted gross margin | about 55% | n/a |
One small caution: the gross margin guide of about 55% is a point below this quarter’s 56%. Rack-scale systems include memory, networking and other parts AMD buys from suppliers, so they tend to carry thinner margins than selling a chip on its own. Bigger revenue, slightly thinner slice. Apple’s report earlier this week showed how touchy investors are right now about margin outlooks, so watch this line.
Operating cash flow was $1.2 billion in the quarter, down from about $2.16 billion a year earlier. Capital spending also jumped to $648 million from $258 million.
Why would cash fall while profit doubles? Usually it’s working capital: a company building lots of inventory ahead of a big product ramp, or waiting longer to get paid by customers. That fits a Helios ramp, but it’s worth checking on the earnings call and in the 10-Q. A gap between reported earnings and cash that lasts more than a couple of quarters is a yellow flag, as Amazon investors were reminded last week.
AMD reported into a mixed market. The Nasdaq rose 0.83% and the S&P 500 gained 0.36%, while the Dow slipped 0.38%, TheStreet reported. Chip stocks led the Nasdaq higher.
It’s also midterm Election Day. CNBC reported, via a StockTitan market recap, that prediction-market traders gave Democrats close to a 75% chance of winning the Senate, and that a sweep of both chambers isn’t priced in. So Wednesday’s trading could swing on politics as much as on AMD’s numbers.
It’s a sharp contrast with Intel, whose Q3 report last week paired a decent quarter with a soft forecast and a falling stock. In chips right now, guidance is everything.
If you own AMD directly, this quarter supports the AI thesis with real numbers rather than promises. But the stock now carries big expectations. Hitting $17 billion is the bar, and anything short of it next quarter will get punished.
If you own a broad index fund, you already have some AMD, along with Nvidia, Broadcom and the rest. Strong results across AI chip suppliers help explain why tech keeps carrying the S&P 500, and also why the index is more concentrated in one theme than it used to be.
If you’re thinking about buying after a 7% pop, be careful about chasing. Earnings gaps sometimes fill in the following days, especially in a jumpy election week. Some investors split a purchase into a few smaller buys over several weeks to avoid going all in at one price. If you want a quick read on a stock before you act, StocksWisdom shows its sentiment, technical signals and a 30-day forecast in one place.
Yes. Adjusted EPS was $2.09 against $1.94 expected, and revenue of $13.38 billion topped the $13.06 billion estimate. Fourth-quarter guidance of about $17 billion also came in well above the consensus near $16.23 billion.
Mostly the guidance. A beat on the quarter was expected, but a forecast about $800 million above estimates suggests AI demand is speeding up, not peaking.
It’s AMD’s rack-scale AI system, combining MI450 Series GPUs and EPYC processors in a full data center cabinet. It competes with Nvidia’s rack systems and is the main reason AMD expects faster growth in Q4.
Do you think AMD can close the gap with Nvidia, or is the $17 billion guide already priced in? Tell us in the comments.
Not financial advice. Do your own research.